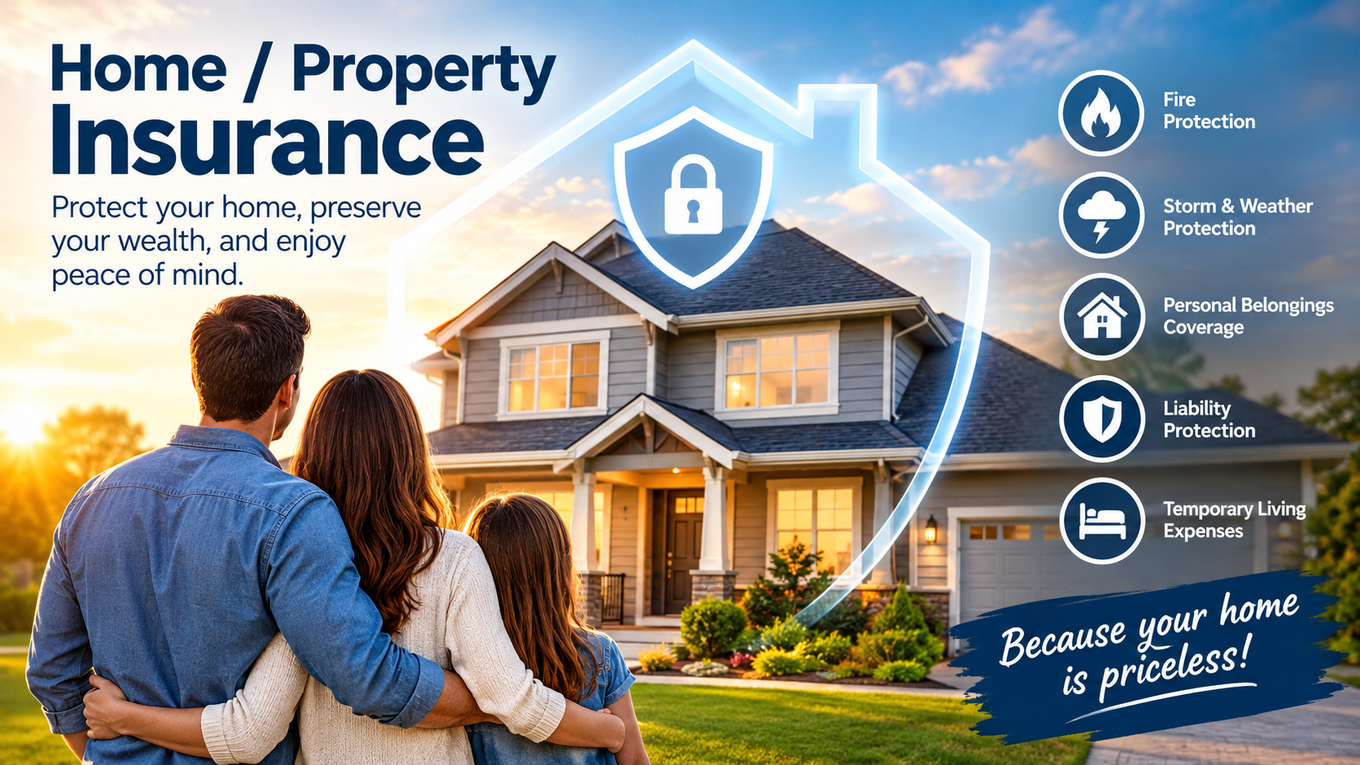
Home / Property Insurance: Protect Your Home, Preserve Your Wealth, and Enjoy Peace of Mind
Imagine coming home after a long day at work, opening the front door, and experiencing that unique feeling of comfort, security, and belonging. Every room holds memories, every piece of furniture represents an achievement, and every detail reflects the effort you have invested in creating a special place to live. Now, imagine losing everything in a matter of minutes because of a fire, a severe storm, an unexpected water leak, or another event capable of causing significant financial damage.
This is a reality many families prefer not to imagine, but it can happen when least expected. That is precisely where Home / Property Insurance, commonly known as homeowners insurance or property insurance, plays an essential role.
More than a simple insurance policy, this type of protection represents a financial strategy for preserving your property, reducing worries, and facing unexpected situations with greater confidence. After all, your home is not merely a building made of bricks and concrete. It represents years of hard work, dreams fulfilled, and the future you want to build for your family.
What Is Home / Property Insurance?
Home / Property Insurance is a type of insurance designed to protect residential properties and, depending on the policy, certain belongings and liabilities associated with the property. It is widely recognized in the United States and other international markets, where homeowners and, in some cases, renters use insurance to reduce the financial consequences of unexpected events.
Coverage may include damage caused by fires, certain weather events, vandalism, and other risks specifically identified in the policy. Some policies also provide protection for personal belongings, temporary living expenses, and personal liability to third parties.
However, every policy has its own conditions, coverage limits, deductibles, and exclusions. Flooding, earthquakes, normal wear and tear, and other risks may require additional coverage or may not be included in standard protection.
Therefore, choosing home insurance does not simply mean purchasing the first plan available. It means understanding your needs and finding protection that matches the value of your property and the risks to which it may be exposed.
Why Is Protecting Your Property a Smart Decision?
Purchasing a home is often one of the largest financial achievements in a person’s life. Many families spend decades making mortgage payments, saving money, and making sacrifices to reach this goal. For that reason, leaving such an important asset unprotected can represent a significant financial risk.
Imagine that a fire damages part of your home. Beyond the emotional distress, you may need to hire contractors, purchase construction materials, replace appliances, and cover unexpected expenses. Without sufficient financial reserves, recovery can become a long and stressful process.
With an appropriate insurance policy, some of these costs may be covered by the insurance company, depending on the terms and conditions of the contract. Insurance does not eliminate every problem, but it can considerably reduce the financial impact of a covered event.
The real advantage lies in financial predictability. Instead of relying exclusively on personal savings during an emergency, you can have a planned financial protection strategy in place.
Main Types of Home Insurance Coverage
Understanding the available coverage options is essential for making an informed decision. Although options vary depending on the insurer and the country, several types of protection are particularly important.
1. Fire Protection
A fire can seriously damage the structure of a home and destroy valuable possessions. Depending on the policy, insurance may help pay for repairs and replacements related to covered damage.
2. Storm and Weather Protection
Strong winds, hail, and other weather events can damage roofs, windows, and structural components. Coverage depends on the risks included in the contract and the applicable exclusions.
3. Personal Belongings Protection
Furniture, computers, televisions, clothing, and other possessions may be protected against certain covered events. It is important to review reimbursement limits and determine whether restrictions apply to high-value items.
4. Personal Liability Protection
Under certain policies, personal liability coverage may help pay compensation and legal expenses associated with covered situations in which the policyholder is legally responsible for causing injury or property damage to another person.
5. Additional Living Expenses
If a covered event makes your home temporarily uninhabitable, some policies may contribute toward additional accommodation or living expenses, subject to contractual limits.
These protections demonstrate how insurance can provide assistance in different situations. The key is to carefully evaluate which risks are most relevant to your property and lifestyle.
The Cost of Being Unprotected
Many people postpone purchasing insurance because they believe unexpected events happen only to other people. Others consider monthly or annual premiums an unnecessary expense, especially when they are trying to save money.
However, this decision can have significant financial consequences.
The cost of repairing a damaged roof, replacing destroyed appliances, or restoring rooms affected by a fire may exceed the premiums paid over many years. Although it is impossible to predict exactly when a problem will occur, it is possible to prepare financially for certain unexpected events.
It is important to understand that insurance is not an investment with a guaranteed return, nor is it a promise of reimbursement for every loss. Instead, it is a mechanism for transferring certain financial risks to an insurance company in exchange for a premium and subject to the conditions established in the policy.
This distinction is fundamental: you do not purchase insurance because you expect an accident to happen. You purchase it so you do not have to face the financial consequences of a covered event entirely on your own.
How to Choose the Right Home Insurance Policy
Finding a suitable policy requires attention, research, and comparison. Price matters, but it should not be the only factor influencing your decision.
First, evaluate the amount needed to rebuild your property. This calculation may differ from the property’s market value because the land and other factors influence the selling price. Consider local construction costs, including materials and labor.
Next, create an inventory of your belongings. Record furniture, household appliances, electronic equipment, and other valuable possessions. Photographs, receipts, and purchase documents can help demonstrate ownership and value if you need to file a claim.
Then, compare different insurance companies. Review their coverage options, reimbursement limits, deductibles, exclusions, and procedures for reporting claims. A cheaper policy may provide significantly less protection.
It is also important to investigate the insurer’s reputation, the quality of its customer service, and the clarity of its contractual terms.
Finally, review your policy periodically. Renovations, new purchases, and changes in rebuilding costs may require adjustments to your coverage.
Home Insurance: Peace of Mind for Homeowners and Renters
Property insurance is not only relevant to people who own their homes. Renters may also need protection, particularly for personal belongings and certain liabilities.
For landlords who rent out properties, specialized policies may provide coverage for the building, personal liability, and, when expressly included, lost rental income resulting from covered events.
People living in rented homes should understand which responsibilities belong to the property owner and which belong to the tenant. The landlord’s insurance does not necessarily protect the renter’s personal belongings.
Every situation requires individual consideration, and the right choice should reflect the type of occupancy, the property’s characteristics, and the needs of the person seeking protection.
Technology and the Future of Home / Property Insurance
Technological developments are transforming the way people purchase and manage home insurance. Today, digital tools can make it easier to compare quotes, access policy documents, and report claims.
Some solutions also use smart sensors to detect water leaks, smoke, and other potentially dangerous situations. When properly installed and used, these devices can help identify problems earlier and reduce certain losses.
In addition, data analysis can help insurers assess risks and develop more personalized products. Nevertheless, consumers should pay attention to privacy, the use of personal information, and the actual conditions of each policy.
The future of home insurance is closely connected to the combination of prevention, technology, and accessible financial protection.
Conclusion: Protect Today What Took Years to Build
Your home is much more than an address. It is the place where your family creates memories, where your plans take shape, and where every achievement finds its place. Protecting this asset means recognizing the value of everything you have built and preparing for life’s uncertainties.
Home / Property Insurance offers a way to reduce certain financial risks, providing greater security for homeowners and, depending on the policy, renters.
Do not wait for an unexpected event to discover how much it would cost to rebuild your life. Research available options, compare coverage, read the contractual terms, and choose protection that matches your needs.