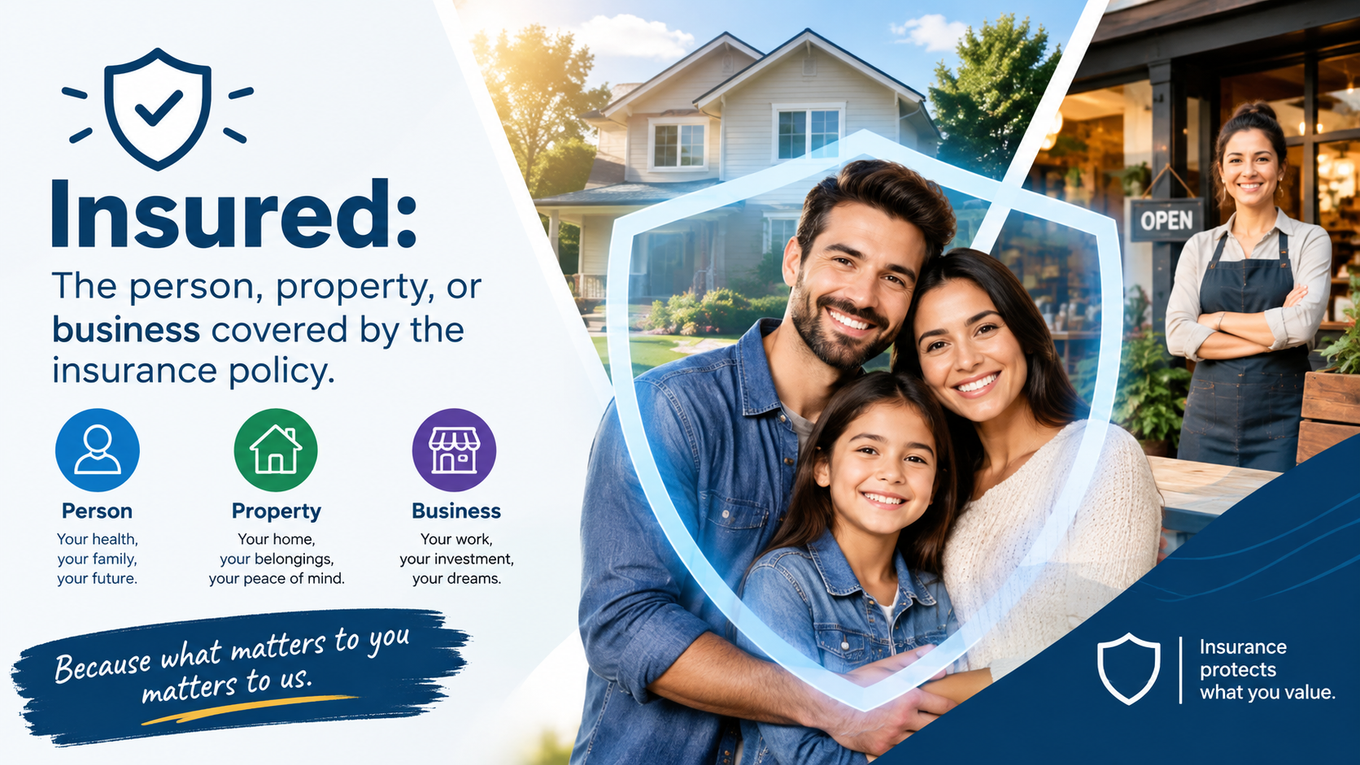
Insured: Understanding Who Is Protected and Why It Matters
on the type of insurance and the wording of the agreement. Not every person associated with a policy automatically receives coverage, and not every loss involving insured property qualifies for compensation. Coverage depends on the policy’s conditions, exclusions, limits, and applicable law.
This is why understanding the insured’s identity and the protection provided is so important. A policy can offer valuable security, but only when its terms match the risks and interests you intend to protect.
Insured, Policyholder, and Beneficiary: Know the Difference
Insurance terminology can sometimes be confusing because several people may participate in the same contract. Three important roles are the insured, the policyholder, and the beneficiary.
The policyholder is the person or organization that owns the insurance policy and is generally responsible for meeting contractual obligations, such as paying premiums.
The insured is the person, property, business, or interest to which the coverage applies. Depending on the contract, the policyholder and insured may be the same individual or separate parties.
The beneficiary is the person or entity designated to receive a benefit under certain policies, particularly life insurance, when the contractual conditions are satisfied.
Consider a parent who purchases life insurance covering their own life and names their child as the beneficiary. The parent is both the policyholder and the insured, while the child is the beneficiary. In another arrangement, an employer may provide insurance coverage to employees, making the relationship between the policyholder and insured different.
Recognizing these distinctions can help prevent misunderstandings about who is protected, who controls the policy, and who may receive payment following a covered event.
Why Identifying the Insured Correctly Matters
Accurate identification is one of the foundations of effective insurance protection. Names, addresses, vehicle details, property descriptions, business information, and other relevant details should reflect the circumstances required by the policy.
Incorrect or outdated information can create complications when a claim is submitted. Depending on the nature of the error, the policy terms, and applicable law, inaccurate disclosures may affect coverage, delay processing, or lead to disputes.
Imagine purchasing home insurance and assuming that a recently acquired property is automatically included in an existing policy. If the contract requires the property to be specifically identified, that assumption could create an unexpected coverage gap. Similarly, a business that changes its operations without reviewing its insurance arrangements may discover that certain new activities are not covered.
These examples demonstrate why policyholders should verify the identity of the insured and review the scope of protection whenever important circumstances change.
Taking a few minutes to confirm these details can help avoid unnecessary confusion and strengthen confidence in your insurance arrangements.
Protecting People Through Insurance
When an individual is the insured, coverage may help manage specific financial risks associated with health, life, disability, travel, or other circumstances.
Health insurance may help pay eligible medical expenses according to the plan’s conditions. Life insurance may provide a financial benefit to designated beneficiaries following the insured person’s death, subject to the contract. Disability insurance, where available, may help replace part of an insured person’s income when qualifying conditions prevent them from working.
These protections can be especially important for families with dependents, individuals with significant financial obligations, and people who want to prepare for unexpected expenses.
However, personal insurance should never be selected solely because a product sounds comprehensive. The insured should understand the applicable limits, waiting periods, exclusions, eligibility requirements, and claim procedures.
Choosing coverage based on real needs rather than assumptions helps ensure that the policy provides practical value. A well-informed decision can offer greater financial preparedness and help individuals approach uncertainty with more confidence.
Protecting Property and Businesses
Insurance can also protect physical assets and commercial interests. In property insurance, the insured interest may involve a home, commercial building, equipment, inventory, or other specified assets. Depending on the contract, covered events may include fire, theft, certain weather-related damage, or other defined risks.
For vehicle insurance, protection may apply to a specified automobile and may include eligible damage, theft, or liability coverage. The exact scope varies by policy, making it essential to understand who is covered to drive the vehicle and which circumstances qualify for protection.
Business insurance introduces additional considerations. A company may seek protection for buildings, machinery, stock, professional liability, or interruptions to normal operations. Depending on the agreement, a policy may identify the business itself, particular subsidiaries, employees acting within defined responsibilities, or other covered parties.
Business owners should review their coverage when opening new locations, acquiring equipment, hiring employees, or introducing new services. Changes in operations can create new risks that existing insurance may not automatically cover.
By accurately identifying insured assets and activities, individuals and organizations can make more informed decisions about managing their financial exposure.
How to Confirm That the Right Person or Property Is Covered
Understanding your insurance protection begins with reviewing the policy documents carefully.
First, identify the named insured and check whether other individuals, properties, or entities are included. Next, review the coverage sections to determine which risks are insured and under what circumstances benefits may be available.
Pay attention to exclusions, deductibles, coverage limits, waiting periods, and notification requirements. If the policy includes additional insured parties or special endorsements, verify what those provisions mean and whether they apply to your situation.
You should also update the insurer when relevant changes occur, following the contract’s requirements. Marriage, changes in household composition, property purchases, business expansion, and vehicle replacement may affect insurance needs.
If anything is unclear, request written clarification from the insurer or a qualified insurance professional. Keeping policy documents and relevant correspondence organized can also make future claims easier to manage.
The objective is simple: ensure that the protection you believe you have is consistent with the protection your contract actually provides.
The Value of Being an Informed Insured
Insurance cannot eliminate every risk, but appropriate coverage can reduce the financial impact of certain unexpected events. Understanding the insured’s role helps individuals and businesses recognize what their policies protect and where additional planning may be necessary.
An informed approach also encourages responsible decisions. Instead of waiting for an accident, illness, property loss, or business disruption to reveal a coverage gap, you can review your arrangements in advance and address potential weaknesses.
This proactive mindset is especially valuable when financial responsibilities increase or circumstances change. Regular reviews help keep coverage aligned with current needs and can reduce the likelihood of unpleasant surprises.
Conclusion: Make Your Protection Count
The insured is at the heart of an insurance policy because coverage is designed to protect a defined person, property, business, or interest against specified risks. Understanding this role helps clarify who receives protection, which events may qualify for coverage, and what limitations apply.
Whether you are protecting your health, your family, your home, your vehicle, or your business, the right insurance arrangement begins with accurate information and a clear understanding of your policy.
Review your documents, verify who or what is insured, ask questions when necessary, and reassess your protection as life changes.