Insurance Policyholder: Know Your Rights, Strengthen Your Protection, and Secure Your Future
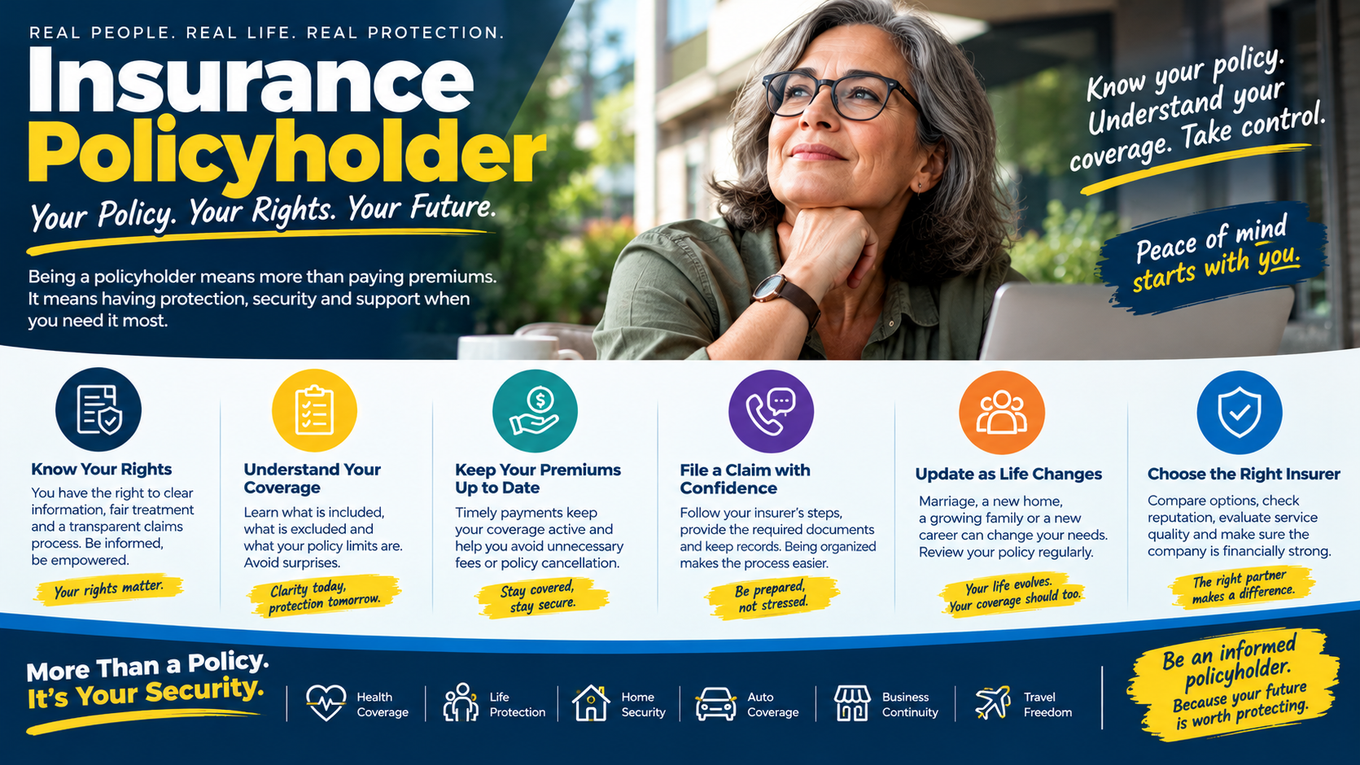
Being an insurance policyholder means more than paying premiums and keeping a policy document in a safe place. It means taking an active role in protecting your financial interests, understanding your coverage, and preparing for unexpected events that could affect your life, family, property, or business. In a world where uncertainty is unavoidable, informed policyholders are better positioned to make confident decisions, recognize the value of their protection, and respond effectively when they need support.
Whether you have health, life, home, auto, travel, or business insurance, understanding your responsibilities and rights can make a meaningful difference. The more familiar you are with your policy, the easier it becomes to identify potential gaps, avoid misunderstandings, and make informed choices about your financial security.
Understanding the Role of an Insurance Policyholder
An insurance policyholder is the individual or organization that owns an insurance policy and is generally responsible for meeting its contractual obligations, including paying premiums when due. Depending on the policy, the policyholder may also be the insured person, but these roles are not always identical. For example, one person may own a life insurance policy covering another individual, while a designated beneficiary may receive the benefit if a qualifying event occurs.
This distinction matters because insurance contracts define who receives coverage, who must fulfill particular obligations, and who may be entitled to benefits. Understanding these details helps prevent confusion, especially when policies involve family members, employees, business partners, or multiple beneficiaries.
A policyholder’s relationship with an insurer should be based on clear information, accurate documentation, and a shared understanding of the agreement. Reviewing these fundamentals is an important first step toward making insurance work effectively for your needs.
Why Understanding Your Insurance Policy Matters
An insurance policy is a contractual agreement that specifies the circumstances under which coverage applies. It also establishes limits, exclusions, deductibles, waiting periods, and procedures for submitting claims. Although these details may appear complicated, they determine the actual protection available when an unexpected event occurs.
Imagine experiencing a vehicle accident and discovering that certain repairs are excluded from your coverage. Or consider a homeowner who assumes that every type of water damage is insured, only to discover that the policy distinguishes between covered incidents and excluded causes. These situations illustrate why relying on assumptions can lead to frustration and unexpected expenses.
Taking time to understand your policy before a problem arises can help you recognize what is covered, what is not, and what steps you must follow to request benefits. It can also help you identify whether your current coverage remains appropriate as your circumstances change.
Knowledge is one of the most valuable tools an insurance policyholder can have. It allows you to approach your coverage with greater confidence instead of waiting until a crisis exposes an important misunderstanding.
Know Your Rights and Responsibilities
Insurance policyholders generally have contractual rights, although the exact protections available depend on the policy and applicable law. These may include receiving policy information, accessing explanations of coverage, submitting eligible claims, receiving decisions according to applicable requirements, and using available complaint or appeal procedures.
In many jurisdictions, consumer protection rules also establish standards for fair treatment, disclosure, privacy, and claims handling. Policyholders should familiarize themselves with the regulations governing their insurance, particularly when a dispute arises or an insurer denies a claim.
Rights come with responsibilities. Providing accurate information during the application process is essential because incorrect or incomplete disclosures may affect coverage or claim outcomes. Policyholders should also pay premiums according to the agreed terms, report relevant changes when required, and comply with reasonable policy conditions.
When an incident occurs, maintaining accurate records can be especially helpful. Photographs, receipts, repair estimates, medical documents where relevant, correspondence, and claim reference numbers may support the claims process. Always follow the insurer’s reporting instructions and retain copies of important communications.
Understanding both sides of the agreement helps policyholders protect their interests while maintaining a transparent relationship with their insurance provider.
Choosing Coverage That Matches Your Life
Your insurance needs are not necessarily permanent. A policy that was suitable several years ago may no longer provide adequate protection after a major life change. Marriage, parenthood, purchasing a home, changing careers, acquiring a vehicle, or starting a business can introduce new financial responsibilities.
Life insurance may be important for individuals whose families depend on their income. Health insurance may help manage eligible medical expenses. Home insurance can protect against specified property risks, while auto insurance may provide financial protection for covered accidents and liability. Business insurance can help organizations manage operational exposures and certain legal claims.
The objective is not to purchase every available product. It is to determine which risks could cause the greatest financial harm and evaluate appropriate ways to manage them.
Review your coverage periodically, paying particular attention to policy limits, deductibles, beneficiaries, exclusions, and premium changes. If your financial responsibilities have increased, consider whether your existing protection remains sufficient. If your circumstances have changed significantly, compare available alternatives before making adjustments.
A thoughtful review can help prevent both underinsurance and unnecessary spending on coverage that does not serve your current priorities.
The Importance of Managing Premiums and Policy Documents
Premium payments are a fundamental part of maintaining insurance coverage. Missing a payment may result in fees, a lapse, or other consequences depending on the contract and applicable regulations. Setting reminders, using reliable payment methods, and checking renewal notices can help reduce the likelihood of accidental interruptions.
However, affordability should never be the only factor when comparing policies. A lower premium may come with higher deductibles, narrower coverage, or lower benefit limits. Comparing the overall value of a policy is more useful than focusing exclusively on its price.
Organization is equally important. Keep your policy documents, payment confirmations, insurer contact details, beneficiary information, and claims correspondence accessible and secure. Make sure you understand how to report an incident and which documents may be required.
For policies intended to protect family members, ensure that appropriate individuals know where essential information can be found. This can simplify communication and help loved ones understand what to do if they need to contact the insurer.
Good policy management reduces avoidable complications and makes it easier to use the protection you have arranged.
What to Do When You Need to File a Claim
Filing an insurance claim can feel stressful, particularly when it follows an accident, illness, property loss, or another disruptive event. Knowing the process in advance can make the experience more manageable.
Begin by reviewing your policy’s notification requirements and contacting the insurer through an official channel. Explain what happened accurately and provide the requested information. Keep copies of submitted documents, record important dates, and save communications related to your claim.
Avoid assuming that every loss is automatically covered. The insurer will generally assess the circumstances against the policy terms, applicable exclusions, and relevant legal requirements. If additional information is requested, respond within the specified deadlines whenever possible.
If a claim is denied or the proposed payment appears inconsistent with your understanding of the policy, request a written explanation. Compare the decision with the contract and ask the insurer to clarify the reasoning. Depending on the circumstances and jurisdiction, you may be able to request an internal review, contact a consumer protection authority, consult an insurance ombudsman, or seek independent legal advice.
Remaining organized and informed can help you address disagreements constructively and understand the options available to you.
Building a Stronger Relationship With Your Insurer
Effective communication can improve your experience as a policyholder. Ask questions when policy language is unclear, confirm important details in writing, and make sure you understand any changes before accepting them.
Evaluate insurers based on more than advertising. Consider their reputation, customer service, financial strength where reliable information is available, complaint-handling practices, and the clarity of their policy terms. Independent comparisons and qualified professional advice can help you evaluate alternatives.
Be cautious of offers that promise unusually comprehensive protection at implausibly low prices. Verify that an insurer or intermediary is properly authorized where required, and never share sensitive financial information through unverified channels.
A productive relationship with an insurer should involve understandable information, appropriate service, and realistic expectations about the coverage purchased.
Take Control of Your Insurance Protection
Being an informed insurance policyholder is an ongoing responsibility, not a one-time decision. It involves understanding your agreement, keeping information current, paying attention to changing needs, and knowing how to act when coverage becomes necessary.
Insurance cannot prevent every loss or eliminate uncertainty. However, suitable coverage can help reduce the financial impact of specified events and support a more stable recovery when life takes an unexpected direction.
Start today by reviewing your policy, identifying questions that remain unanswered, checking your coverage limits, and confirming that your personal information is accurate. If necessary, compare alternatives and seek professional guidance before making significant changes.
Your protection is too important to leave to assumptions. By becoming an informed, proactive policyholder, you can make better decisions, strengthen your financial preparedness, and approach the future with greater confidence. The most effective insurance strategy begins with understanding what you have, knowing what you need, and taking deliberate steps to protect what matters most.